After a car crash, dealing with injuries, medical appointments, and vehicle repairs can be overwhelming. Then comes another challenge: dealing with insurance companies. While consumers may expect an insurer to simply determine what happened and pay a fair claim, the claims process can be much more complicated. Adjusters may request recorded statements, seek broad access to medical records, or make settlement offers before the full extent of an injury is known.
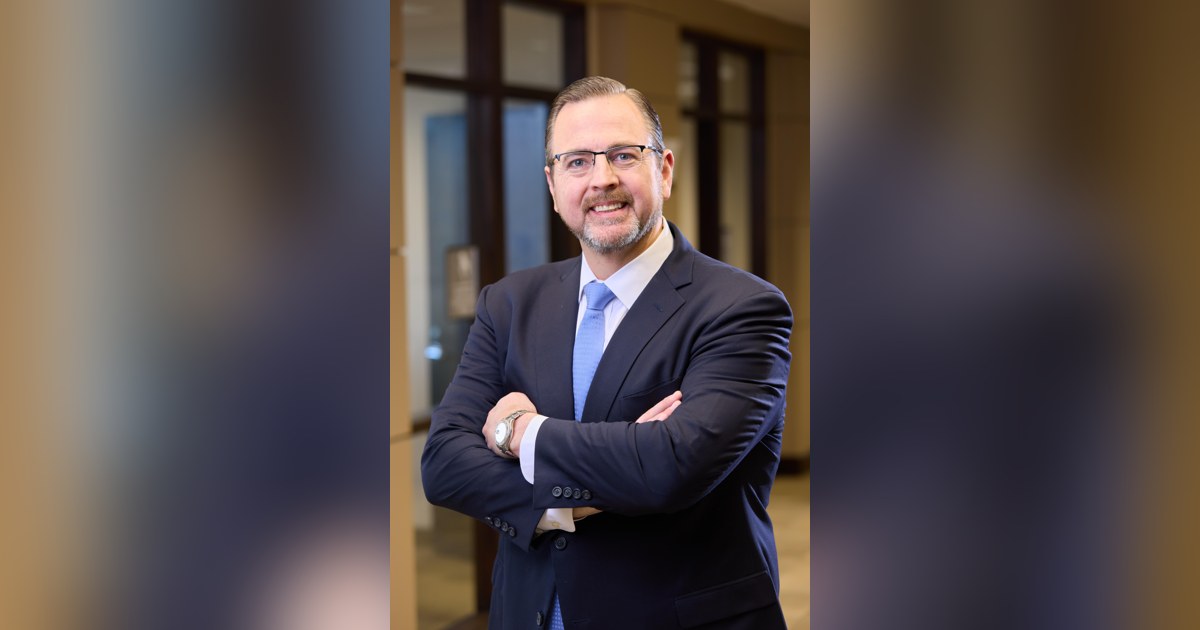
Ryan L. Thompson, founder and managing partner of Thompson Law, says injured consumers should understand how the claims process works before making decisions that could affect their recovery. Thompson previously defended corporations before establishing his personal injury practice, giving him experience with how insurers and defense teams evaluate and resolve claims.
One common tactic is the recorded statement. Soon after a crash, an insurance adjuster may ask an injured person to provide a recorded statement about what happened and how they are feeling. In Texas, a participant in a telephone conversation generally may record that conversation without obtaining the other participant’s permission. Consumers should therefore assume an insurance call may be recorded rather than assume a conversation is off the record. That distinction matters when injuries are still developing. Someone who says they feel “fine” shortly after an accident may later discover an injury that was not immediately apparent. There is also an important difference between dealing with your own insurer and the other driver’s insurer. A standard Texas personal auto policy contains a duty to cooperate with your own insurance company. Thompson cautions that an injured third party does not have the same contractual obligation to provide a recorded statement to the other driver’s insurer.
Another issue is the fast settlement offer. A quick check can seem like welcome news when medical bills and other expenses are mounting. But speed is not necessarily the same thing as a complete and fair evaluation of a claim. The danger is settling before doctors know the extent of an injury or how long recovery may take. Once a claimant signs a release and resolves the claim, the opportunity to seek additional compensation for that claim generally ends. Texas Insurance Code Section 541.060 prohibits an insurer from refusing to pay certain claims without conducting a reasonable investigation and requires good-faith settlement efforts in specified circumstances when liability has become reasonably clear.
Broad access to medical history is another concern. An authorization may give an insurer access to medical information extending beyond treatment directly connected to the accident. That can include older conditions or treatments that may become part of the insurer’s evaluation of whether an injury resulted from the crash. Thompson said nothing in Texas law requires an injured third party to provide the other driver’s insurer with unlimited access to medical records. Consumers may instead limit an authorization by provider and date or offer to supply relevant records directly.
Technology can also play a role. In 2010, Allstate reached a multistate regulatory settlement involving the insurer’s use of the Colossus claims-handling software. The insurer agreed to a $10 million regulatory settlement and reforms governing how the software was used. The historical case should not be interpreted as proof that insurers today systematically underpay claims using software. New York’s insurance superintendent said the examination did not find systemic underpayment of bodily-injury claims.
Finally, delay and repeated requests can stall a claim. Keep track of dates, phone calls, documents submitted, and the names of adjusters. Some Texas claims involving a person’s own insurer are also subject to statutory deadlines. The consumer must distinguish those deadlines from third-party claims involving the other driver’s insurer. Keeping copies of correspondence and maintaining a timeline can help consumers know what information has already been supplied and what remains outstanding.
For Thompson, the takeaway for injured consumers is simple: don’t treat every request from an insurance company as routine paperwork. Understand what information is being requested, what rights may be affected, and what accepting or signing a document means before making a decision.